Does a robot cost $2 or $35 an hour? A multitrillion-dollar market depends on how the answer
· Fortune
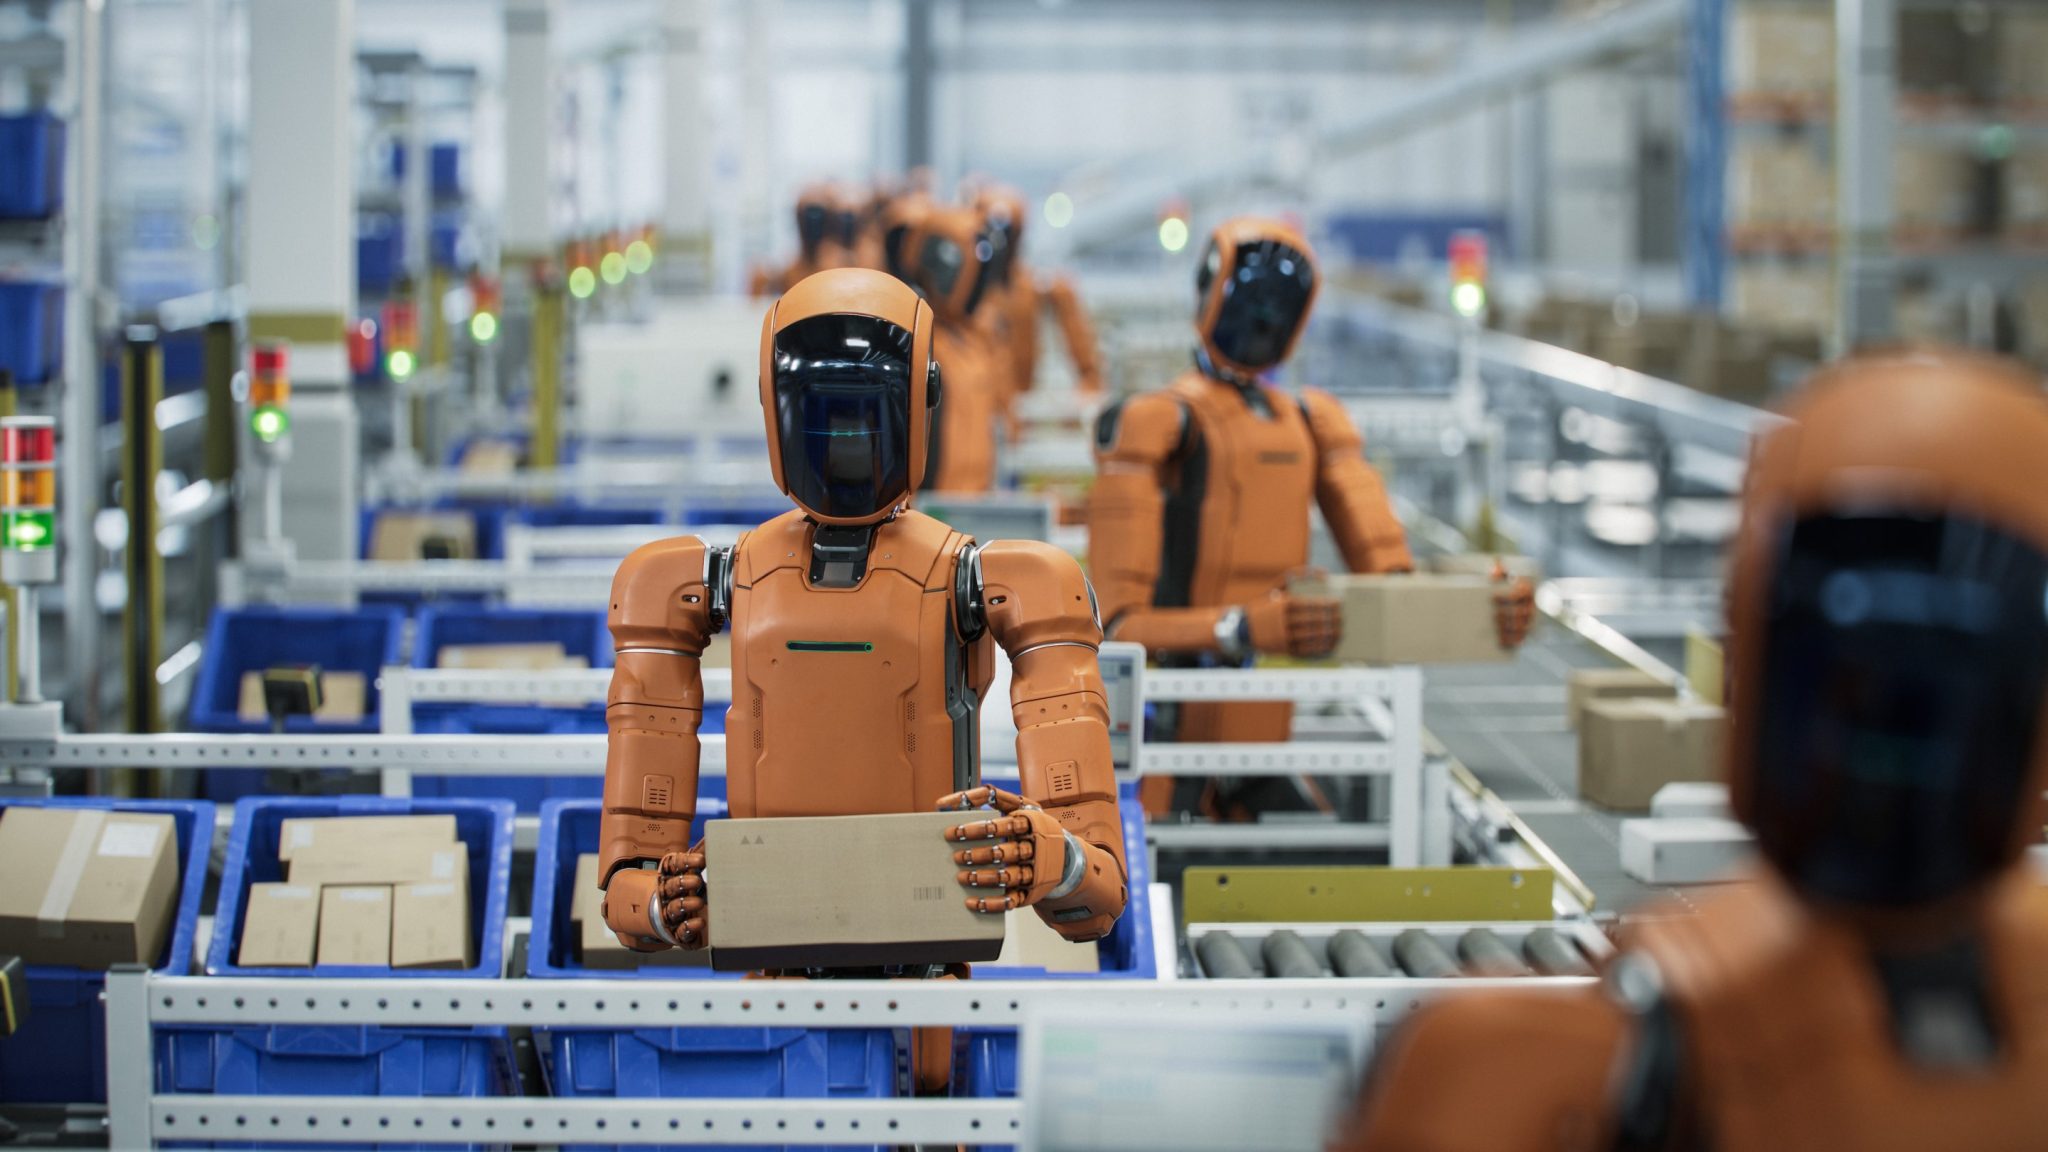
Do robots actually save enterprises money?
Visit biznow.biz for more information.
Depending on whom you ask, a robot costs $2 an hour, according to a Roland Berger study earlier this year; $10 to $12, according to JPMorgan or more than $35, according to reports on early industrial deployments.
These figures appear to contradict one another. In fact, they expose the real question facing the physical AI industry: How much useful work can a robot reliably perform?
Enterprises do not need robots that are inexpensive in theory. They need dependable labor in the messy conditions of a factory, warehouse, or distribution center.
That distinction will determine whether physical AI remains an expensive collection of pilots or becomes a labor market measured in trillions of dollars.
The economics depend on utilization
A robot’s hourly cost is relatively simple to calculate. Divide its purchase or lease cost by the productive hours it works over its life, then add power, maintenance, software, integration, and supervision.
The variable that changes everything is productive time.
In Roland Berger’s equation, the $2 an hour covers energy, software, network, and scheduled maintenance. It excludes the purchase or the lease of the machine. This equates to the running cost at volume, not the cost of a deployment. When placed against the average U.S. warehouse human wages, that $2 an hour only wins if the robots are running 60-70% of the time.
Consider a $90,000 industrial robot amortized over five years. At 2,000 working hours per year, the hardware contributes about $9 to each operating hour. Add maintenance and other expenses, and the total might approach $12.
But if the robot works only 1,000 hours a year, the hardware cost per productive hour doubles. If it operates only during occasional peaks or spends long periods waiting for a task, the effective cost rises further.
Same robot. Same price. Different schedule.
JPMorgan estimates it currently takes about two humanoids to match the output of one human worker. That doubles the effective hourly cost. But, productivity per hour improves with software, while cost per hour improves only with hours. The productivity problem is being solved in labs. The utilization problem has to be solved on the floor.
Some describe the marginal cost of running a robot at scale. Others include equipment and integration. Still others reflect early deployments with low utilization and extensive human supervision.
The robot’s sticker price matters. Its schedule matters more.
The truth in Agility’s filing
The clearest public evidence is Agility Robotics’ S-4, which was filed ahead of its merger with Churchill Capital Corp XI. Its Digit robots have logged more than 65,000 hours across nine customer sites, including GXO, Schaeffler and Toyota Motor Manufacturing Canada. The filing shows $1.78 million in 2025 net sales against a $140.2 million operating loss and $300 million in milestone-contingent orders from a single customer.
It also lays out Agility’s own cost model for its next robot which is roughly $400,000 over a five-year life. Run one shift of 2,000 hours a year, and that is about $40 an hour, while two shifts are running close to $20 an hour. Because Agility’s fully loaded worker benchmark is $30 an hour, the robot becomes cheaper only after it runs more than 2,700 hours a year.
Factory floors are no laboratories
High utilization cannot rescue a robot that fails whenever conditions change.
Robotics has produced impressive demonstrations for decades: robots folding shirts, making coffee, moving boxes, and completing intricate tasks in controlled environments. The trouble begins when they leave the lab.
Factories and warehouses are full of variation. Objects arrive in unexpected positions. Packaging changes. A person steps into an aisle. Equipment gets moved. A task that appeared simple in a demonstration becomes a stream of exceptions.
This gap between a perfect demo and dependable production is the central challenge in physical AI.
A robot that requires an engineer every time its environment changes is not autonomous labor. It is an ongoing integration project.
The winning companies will therefore be measured by less glamorous questions: Can their systems perform useful work consistently? Can they move between tasks without expensive reintegration? Can they operate for enough hours to deliver an attractive cost per completed job?
Those questions point to a different business model.
Don’t sell a robot. Sell work.
Under a Labor-as-a-Service model, the customer is not primarily buying equipment. The customer is buying an outcome: pallets moved, trailers unloaded, parts delivered to an assembly line, or packages sorted.
Instead of asking an operations leader to make a large capital bet on unfamiliar technology, a provider can price its service against the work performed. The provider assumes greater responsibility for deployment, maintenance, software, and uptime. The customer pays for productive capacity.
This model forces robotics companies to confront utilization directly. A vendor paid for completed work cannot hide behind a successful pilot or an ambitious unit forecast. Its economics depend on keeping the machines productive.
For customers, the relevant comparison is not a robot’s theoretical hourly cost versus a worker’s wage. It is the cost and reliability of the complete service versus the fully loaded cost of getting the work done today—including overtime, turnover, vacancies, safety incidents, and lost output.
This is especially significant in manufacturing and logistics, where labor shortages already constrain production. Many of the strongest initial applications are the dull, dirty, and dangerous tasks that go unfilled, contribute to injuries, and pull people away from higher-value judgment and exception handling.
One of us argued in March that the winners in Physical AI would be the most operationally disciplined companies rather than the most visible. That claim was intuition but the cost figures above provide the proof.
Start with a wedge, not a universal worker
The industry’s most visible ambition is a general-purpose humanoid capable of doing almost anything. That vision may eventually be realized, but it is not the most credible route to near-term scale.
A better strategy is to start with a narrow wedge: a recurring problem in an environment structured enough to support reliable operation, yet complex enough to create a defensible advantage.
Warehousing, automotive manufacturing, food processing, and industrial material movement are promising not because they produce the best videos, but because the work is repetitive, demand is persistent, and many facilities operate across multiple shifts.
A company might begin by automating pallet movement rather than attempting every task on the factory floor. If it performs that job reliably, it generates something more valuable than a demonstration: real-world data.
Every deployment exposes the system to variations a laboratory cannot reproduce. That data improves the models. Better models handle more exceptions. Greater reliability opens adjacent tasks. More tasks increase the hours each system can work, improving utilization and lowering the effective cost.
More deployments create more data. More data expands capability. Greater capability creates more work. More work improves the economics.
That is how a narrow wedge becomes a platform.
The next labor platform
The global market for manual labor is measured in tens of trillions of dollars. Capturing even a small share would create enormous companies. But the opportunity will not be won by putting more robots into pilots.
It will be won by turning machines into dependable labor capacity.
The leaders will focus first on repetitive, necessary work that exists across multiple shifts. They will enter through a narrow operational wedge, learn from real production environments, and expand as their systems become more capable. They will combine hardware, intelligence, deployment, and service into a reliable unit of work.
The physical AI revolution will not be defined by how many robots companies sell. It will be defined by how much useful work those robots complete.
Disclosure: Navin Chaddha is Managing Partner at Mayfield, an investor in Rhoda AI, a robot foundation model company. Mayfield holds no other Physical AI positions. The opinions expressed in Fortune.com commentary pieces are solely the views of their authors and do not necessarily reflect the opinions and beliefs of Fortune.
This story was originally featured on Fortune.com