AI in regulated industries: BofA and S&P on the huge gains to be had, and the risks of rushing in
· Fortune
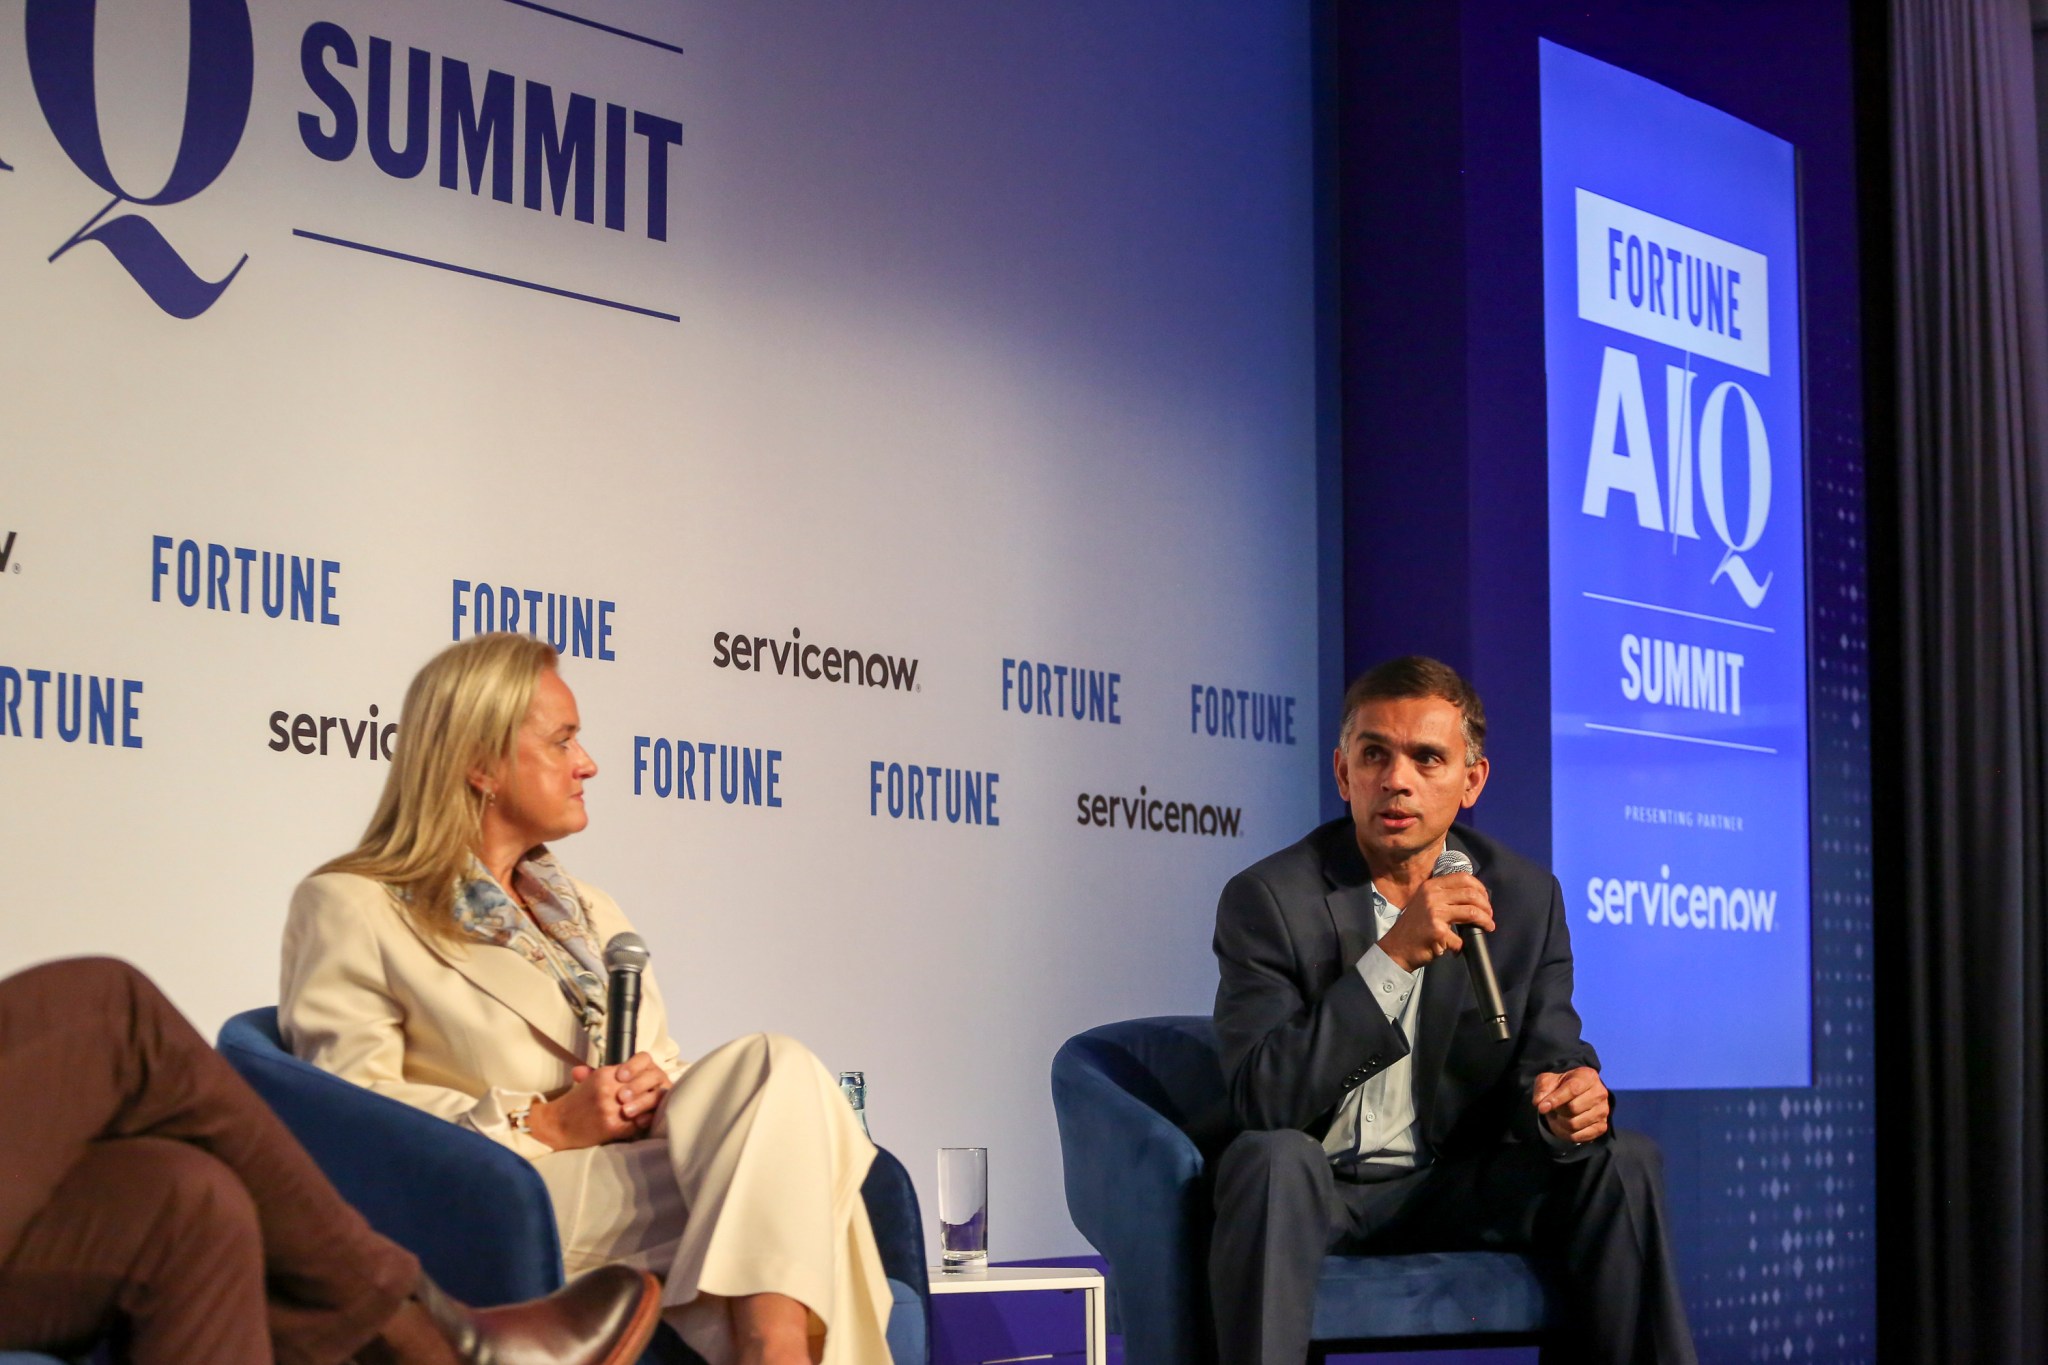
Bank of America’s chief technology and information officer said one of the most common AI mistakes is reaching for it first. His bank also plans to double its AI budget next year.
“One of the biggest mistakes we see us and others doing is rush to AI as a solution,” Hari Gopalkrishnan said at Fortune‘s AIQ Summit in New York, “when deterministic models do a plenty good job.”
Visit umafrika.club for more information.
Gopalkrishnan appeared with Sally Moore, S&P Global’s chief client officer and co-head of Kensho Data & Platforms. Fortune Editorial Director Andrew Nusca moderated.
Bank of America: simple tools first
Gopalkrishnan said the bank starts with what clients need and a “process inventory” of the steps behind their requests. It often decides against AI — “plenty of times,” he said. A mobile app or a real-time decision rule can be the better answer.
Every AI project also goes through a review that covers 16 “pillars” of risk, including privacy, bias, workforce impact and intellectual property. “We’re not going to implement a chatbot that only answers to certain accents,” he said.
He said the bank has used AI for more than a decade, starting with fraud models. Its Erica virtual assistant has handled 3.6 billion transactions, he said, and without it the bank would need 11,000 more people to answer the calls. A March bank press release counted Erica’s client interactions at more than 3.2 billion.
The caution comes with heavy spending. CEO Brian Moynihan said in September that about 140 AI uses cost $400 million and generate $800 million in benefit, and that the AI expense budget will double next year.
That spending is routed carefully, and Gopalkrishnan said the bank is model-agnostic. An orchestration layer (called Orchestra, naturally) sends simple classification tasks to approved open-weight models running on the bank’s own GPUs, and harder reasoning to proprietary models. He said this also helps control token costs. In wealth management, advisors can now prepare for client meetings in “seconds and minutes,” work that used to take days and weeks, he said.
On agents, the bank isn’t hurrying toward autonomy. “There is so much juice to be squeezed right now with assistive agents that are actually working with humans in the loop,” he said. The bank will go further as control infrastructure improves.
He also addressed security, and said AI models are getting better at finding software vulnerabilities, so patching and secure development matter whether or not a company uses AI. The stakes go beyond any one bank, he said: if a small bank somewhere has a problem, people lose faith in the financial system.
S&P: data as the currency
Moore said her 160-year-old company is repositioning itself —aggressively and carefully. S&P is the world’s largest credit rating agency, and one of the largest index providers, and much of its financial data feeds regulated workflows, she said. “Data is the currency within AI,” she said. Clients need accuracy, citations, and auditability and traceability back to the source.
She credited an early bet. S&P bought the AI company Kensho in 2018, and that has “given us an advantage,” she said, explaining that S&P has since put Kensho at the center of the business. On July 6, it split Market Intelligence into two units. The first, Kensho Data & Platforms, pairs “Kensho Data,” the client-facing data and AI delivery layer, with a Platforms group that houses Capital IQ, Ratings Direct, Visible Alpha and With Intelligence. The second unit is Enterprise Solutions. CEO Martina Cheung said the changes should support revenue growth and better margins.
About two years ago, S&P also created a chief client office, which Moore leads, to work more closely with clients. It has a labs group and what it calls forward-deployed experts, who work with clients on AI.
S&P serves 60,000 clients at different stages of AI adoption, she said. It works with frontier AI labs, puts its data into large language models and productivity tools, and now builds its own agents. Use runs from broad tasks, such as bankers preparing for meetings and pitch books, to specialized agents built for one job.
She gave one example. A tier-one bank with 8,000 bankers was combining S&P content sets in its own platform. S&P helped bring it to production “six times quicker,” she said, and accuracy rose from about 60% when the bank started to 98% afterward. (She didn’t name the bank, and the figures are S&P’s own.) S&P also built a “credit memo builder” agent that keeps humans in the loop and relies on confidence in the underlying data.
Like Gopalkrishnan, she talked about using the right tool for the job. S&P’s deterministic option for language models is an API, so it doesn’t run up heavy token costs, she said. More complex “adaptive data retrieval at scale” costs more. Clients also pay for data, technology and people efficiency from different budgets, so S&P talks with them about a range of outcomes.
Where they part ways
Asked whether he ever chooses against AI, Gopalkrishnan said the simplest answer is often the best one. “AI is not always the right answer,” he said.
Moore agreed, and then took the point further. “I think Hari said it really well. It’s not around the right tool. It’s a little bit about reinvention,” she said. “What am I trying to solve for here? And where can this technology take me?”
Inside S&P, that has meant a central transformation office that brings together technologists and, more recently, data operations.
In the closing lightning round, Moore pointed to “embedded intelligence,” which she said “creates an opportunity to go beyond the clients that you serve today.”
Gopalkrishnan had the last word: “I think anticipating your client needs and serving them where they are will differentiate you in otherwise commoditized space.”
For this story, Fortune journalists used generative AI as a research tool. An editor verified the accuracy of the information before publishing.
This story was originally featured on Fortune.com